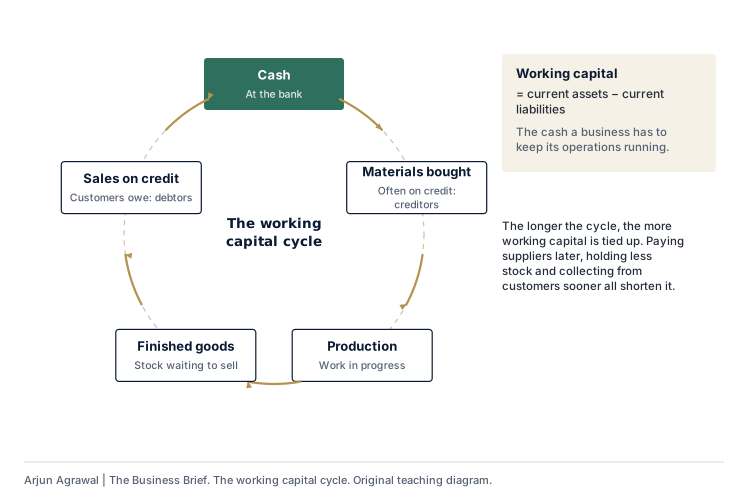
The working capital cycle From cash to stock to debtors and back to cash.Text description
A loop of five stages: cash is used to buy materials, often on credit from suppliers, the creditors; materials go into production as work in progress; they become finished goods held as stock; the goods are sold, often on credit, so customers owe money as debtors; and when debtors pay, the cash returns. Working capital is current assets minus current liabilities, the cash a business needs to keep running. The longer the cycle, the more working capital is tied up; paying suppliers later, holding less stock and collecting from customers sooner all shorten it.
Arjun Agrawal | The Business Brief, https://the-business-brief-dun.vercel.app/diagrams/working-capital-cycle/. Original teaching material, not an IB publication.
The organizations in the teaching cases are fictional unless a case says otherwise.