Diagram · Unit 3 · 3.5, 3.6

The ratio families

SL and HL
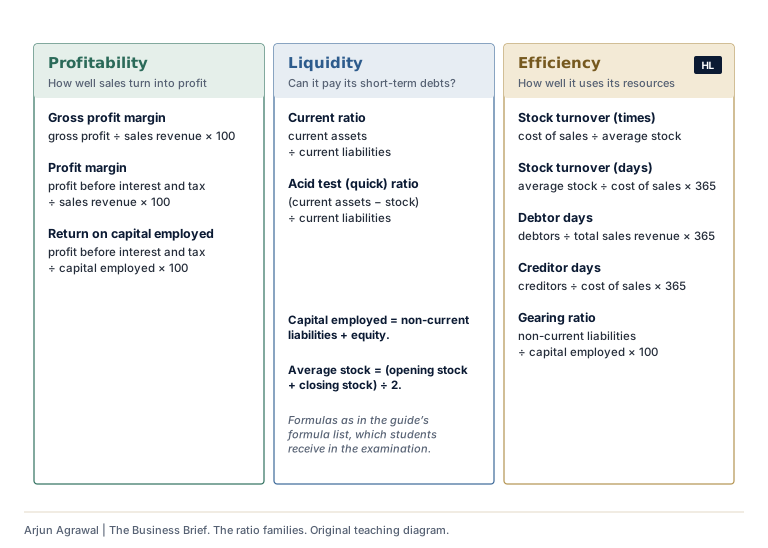
The ratio families and their formulasThree families of ratios with the guide’s formulas. Profitability: gross profit margin is gross profit divided by sales revenue times 100; profit margin is profit before interest and tax divided by sales revenue times 100; return on capital employed is profit before interest and tax divided by capital employed times 100. Liquidity: the current ratio is current assets divided by current liabilities; the acid test ratio is current assets minus stock, divided by current liabilities. Efficiency, for HL: stock turnover in times is cost of sales divided by average stock, or in days average stock divided by cost of sales times 365; debtor days are debtors divided by total sales revenue times 365; creditor days are creditors divided by cost of sales times 365; the gearing ratio is non-current liabilities divided by capital employed times 100. Capital employed is non-current liabilities plus equity, and average stock is opening plus closing stock divided by two.ProfitabilityHow well sales turn into profitGross profit margingross profit ÷ sales revenue × 100Profit marginprofit before interest and tax÷ sales revenue × 100Return on capital employedprofit before interest and tax÷ capital employed × 100LiquidityCan it pay its short-term debts?Current ratiocurrent assets÷ current liabilitiesAcid test (quick) ratio(current assets − stock)÷ current liabilitiesEfficiencyHow well it uses its resourcesHLStock turnover (times)cost of sales ÷ average stockStock turnover (days)average stock ÷ cost of sales × 365Debtor daysdebtors ÷ total sales revenue × 365Creditor dayscreditors ÷ cost of sales × 365Gearing rationon-current liabilities÷ capital employed × 100Capital employed = non-currentliabilities + equity.Average stock = (opening stock+ closing stock) ÷ 2.Formulas as in the guide’sformula list, which studentsreceive in the examination.

The ratio families Profitability, liquidity and efficiency ratios with the guide’s formulas.
Text description

Three families of ratios with the guide’s formulas. Profitability: gross profit margin is gross profit divided by sales revenue times 100; profit margin is profit before interest and tax divided by sales revenue times 100; return on capital employed is profit before interest and tax divided by capital employed times 100. Liquidity: the current ratio is current assets divided by current liabilities; the acid test ratio is current assets minus stock, divided by current liabilities. Efficiency, for HL: stock turnover in times is cost of sales divided by average stock, or in days average stock divided by cost of sales times 365; debtor days are debtors divided by total sales revenue times 365; creditor days are creditors divided by cost of sales times 365; the gearing ratio is non-current liabilities divided by capital employed times 100. Capital employed is non-current liabilities plus equity, and average stock is opening plus closing stock divided by two.

Download SVG

Section 01: Where it is used